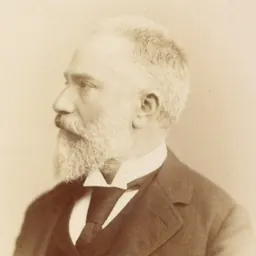
G. Charter Harrison
Anglo-American management consultant and cost accountant
About G. Charter Harrison
Lived 1881 – 1959 (aged 77–78). G. Charter Harrison was a business theorist.
George Charter Harrison (1881 1959 ) was an Anglo-American management consultant and cost account pioneer, known for designing one of the earliest known complete standard cost systems.
Biography G. Charter Harrison was born and educated in England and passed eighth in order of merit in the Anal examination of the Institute of Chartered Accountants in England and Wales. For eight years, up to October, 1916, he was employed by Price, Waterhouse & Company in various capacities: during the later part of this period as manager of the system division of that firm. From January, 1909, to February, 1911, he was comptroller for the Russell, Burdsall and Ward Bolt & Nut Company. At the latter date he returned to Price, Waterhouse & Company to take up the managership of the system division.
In November, 1916, he entered into partnership with the principals of Baker, Sutton & Company, London, England, chartered accountants, under the firm name of Baker, Sutton & Harrison, practicing in New York City. Owing to conditions brought on by the war that firm dissolved in May, 1918. Harrison took out the business and has continued it under his own name.
Chatfield summarized that ïn 1911 Harrison "designed the earliest known complete standard cost system. He elaborated on this system in a series of articles, "Cost Accounting to Aid Production" (1918–1919). His descriptions of accounts, ledgers, and cost analysis sheets were detailed enough to be applied in cookbook fashion." He is also credited for coining the term "fixed budgeting."
Work Harrison is characterized as propagandist in the great field of productive industry. He recognized that the "objective of industry is the production of goods, that everything that hampered the productive process should be eliminated, that impatience with a factory system or detail that hindered, or at least did not help, production was natural, and that cost accounting, instead of being static in accumulating history, should be an active part of the great process of production."
Harrison first explained, why in his days business methods fall short. He states that it is rarely in a large business, that any person can be found who is able to completely recite the routine followed in the handling of an order from its receipt in the mail throughout all the intermediate operations up to the final shipping and billing of the material, nor is it often found that any attempt has been made to analyze such routine with a view to eliminating duplication of work and overlapping of authority. Under such conditions it is hardly to be wondered that the methods employed fall far short of the ideal.
As an illustration of the ramifications involved in the modern manufacturing institution there is shown in the figure a representation of the operations involved in the handling of an order in a concern where the requirements though complex are not by any means exceptional. A consideration of this diagram, which covers only a small section of the routine work of a large organization, will indicate how extremely difficult it would be for the average mind to visualize clearly the innumerable relations and operations involved in the conduct of modern business without the assistance of drawings illustrating these in complete detail.
Unless the practice of machine design is followed and all the parts of the plan or scheme and their various interrelationships are clearly shown on paper it is practically impossible to determine where the routine employed involves duplication of authority and effort and working at cross-purposes, where methods of check are defective or overlap and where essential requirements are overlooked and non-essentials introduced. Due to the absence of such diagrams, the conception in the mind of the average shop or office employee of the methods employed in the operation of a business outside of his own immediate duties is little more than a blur and this applies to the ordinary routine work of an office, to the methods of accounting employed and to the system of controlling the progress of work throughout the shops. It would be difficult to overestimate the educational value of a series of diagrams illustrating all of the routine of the business rendering it possible for every member of the organization to obtain an intelligent conception of the business as a whole and of the relationship of his particular work to the general plan.
Procedure in Planning Routine Work About the "Procedure in Planning Routine Work" Harrison further explained:
In laying out any plan of routine work the logical procedure to be followed is to first clearly define the ends which it is desired to attain and then to determine the simplest and most effective means of realizing them.
This statement would seem so obvious, according to Harrison, that it may be thought that this plan would be followed in a general way by every man of intelligence, but the author has come across cases where years have been spent in an endeavor to introduce satisfactory cost-finding methods by men who at no time have possessed anything more than the vaguest idea of what they were endeavoring to achieve.
To minds like these the reverse of the logical procedure is followed; instead of laying down a general plan and then formulating the details to fit, they start out with small refinements here and there trusting ultimately, doubtless, to be able to coordinate these disconnected ideas in one grand plan. It is not by any means unusual to find cost accountants who have endeavored to develop such refinements of burden distribution that an attempt is made to apportion the cost of heat and light to departments and sub-departments, but who have overlooked such essentials as the control of raw material.
Harrison gives an example of one case where a store accounting system was introduced under which it was necessary for one clerk to devote his entire time to keeping track of the cost of bolts, nuts, and screws which involved an expenditure of considerably less than his salary, and yet under this plan several hundred thousand dollars of other material was shown on the books as being on hand when as a matter of fact it had been used in the manufacture of product shipped and billed months before.
Selected publications Harrison, George Charter. Cost Accounting to Aid Production: A Practical Study of Scientific Cost Accounting. Engineering magazine Company, 1921. Harrison, George Charter. Standard costs: installation, operation and use. Ronald Press Company, 1930. American Management Association, and George Charter Harrison. New Approaches to the Sales Problem. American Management Association, 1937.
Articles, a selection Harrison, George Charter. "Cost Accounting to Aid Production", in: Industrial Management, 1918/19 "I: Application of Scientific Management Principles", Vol 56, No. 4 (Oct. 1918) p. 273-282 "II: Standards and Standard Costs", Vol 56, No. 4 (Oct. 1918) p. 391-398 "III: The Universal Law of System", Vol 56, No. 5 (Dec. 1918) p. 456-464 "IV: The Principle of Burden Distribution." Vol 57, No 1 (Jan. 1919). p. 49-55 "V: Co-operation and Co-ordination." Vol 57, No 2 (Feb. 1919). p. 131-139 "VI: Importance of Deliberation in Introducing Changes." Vol 57, No 3 (March 1919). p. 218-224 "VII: Extension of Application of Scientific Management Principles." Vol 57, No 4 (April 1919). p. 314-321 "VIII: Cost Accounting and the Sales Manager." Vol 57, No 5 (May 1919). p. 400-404 "IX: Conclusion and the Future of Cost Accounting." Vol 57, No 6 (Jun. 1919). p. 483-487
Harrison, G. C. 1920. "Scientific Basis for Cost Accounting." Industrial Management (March): 237—242
Don’t just read it —
keep it.
Full-length biographies made to live with: read them, listen on the way to work, watch them tonight.
- E-book
- Audio
- Video
Instant download · yours to keep · every purchase keeps this site free
Important facts
Related people
Same field, nearest in time


Contemporaries
People whose lives overlapped G. Charter Harrison's
Frequently asked questions
Who was G. Charter Harrison?
anglo-American management consultant and cost accountant (1881-1959)
When was G. Charter Harrison born?
G. Charter Harrison was born in 1881.
When did G. Charter Harrison die?
G. Charter Harrison died in 1959.
What was G. Charter Harrison's occupation?
G. Charter Harrison was a business theorist.
Sources & further reading
· Wikipedia: G. Charter Harrison
· DBpedia: G. Charter Harrison
Cite this page
APA: Biography.guide. (2026). G. Charter Harrison. https://biography.guide/g-charter-harrison/
MLA: "G. Charter Harrison." Biography.guide, https://biography.guide/g-charter-harrison/.
Chicago: "G. Charter Harrison." Biography.guide. https://biography.guide/g-charter-harrison/.
Data last updated: 2026-09-20 · Spot an error? Report a correction.
Page generated 2026-09-27 05:31 UTC