About Rama Cont
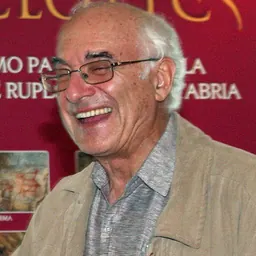
Born 1972. Rama Cont is a French and Iranian mathematician, author, university teacher, research fellow, editor-in-chief and editor, known for Model risk and Systemic risk.
Rama Cont is the Statutory Professor of Mathematical Finance at the University of Oxford.
He is known for contributions to probability theory, stochastic analysis and mathematical modelling in finance, in particular for his work on pathwise methods in stochastic analysis and mathematical models of systemic risk. His doctoral thesis focused on the application of Lévy processes in financial modelling.
Career and achievements Cont started his career as a CNRS researcher in applied mathematics at Ecole Polytechnique (France) in 1998 and held academic positions at Ecole Polytechnique, and Columbia University. from 2012 to 2018. He was elected Statutory Professor in Mathematical Finance at the Oxford Mathematical Institute and professorial fellow of St Hugh's College, Oxford in 2018.
Cont's research focuses on probability theory, stochastic analysis and mathematical modelling in finance. His mathematical work focuses on pathwise methods in stochastic analysis and the Functional Ito calculus.
In quantitative finance he is known in particular for his work on models based on jump processes, the stochastic modelling of limit order books as queueing systems
, machine learning methods in finance and the mathematical modelling of systemic risk.
He was editor in chief of the Encyclopedia of Quantitative Finance.
Cont has served as advisor to central banks and international organizations such as the International Monetary Fund and the Bank for International Settlements on stress testing and systemic risk monitoring. His work on network models, financial stability and central clearing has influenced central banks and regulators . He has given numerous media interviews
on issues related to systemic risk and financial regulation.
Scientific contributions
Causal functional calculus
Cont is known in mathematics for his the "Causal functional calculus", a calculus for non-anticipative, or "causal", functionals on the space of paths. Cont and collaborators built on the seminal work of German mathematician Hans Föllmer and Bruno Dupire to construct a calculus for non-anticipative functionals, which includes as a special case the so-called Ito-Föllmer calculus, a pathwise counterpart of Ito's stochastic calculus.
Subsequent work by Cont and Nicolas Perkowski extended the Ito-Föllmer calculus to functions and functionals of more general irregular paths with non-zero p-th order variation.
Systemic risk modeling
Work by Cont and his collaborators on mathematical modeling of systemic risk and financial stability, in particular on network models of financial contagion and the modeling of indirect contagion via 'fire sales', has influenced academic research and policy in this area.
Central clearing
Cont's research on central clearing in over-the-counter (OTC) markets has influenced risk management practices of central counterparties and regulatory thinking on central clearing. Cont has argued that central clearing does not eliminate counterparty risk but transforms it into liquidity risk, therefore risk management and stress testing of central counterparties should focus on liquidity risk and liquidity resources, not capital.
Risk measurement and Model risk
Cont introduced a rigorous approach for the assessment of model risk which has been influential in the design of model risk management frameworks in financial institutions.
Cont, Deguest and Scandolo introduced the concept of 'risk measurement procedure', an empirical counterpart of the notion of risk measure, and defined a robust class of risk measurement procedures known as 'Range Value-at-risk' (RVaR), a robust alternative to Expected shortfall.
Cont, Kotlicki and Valderrama define the concept of Liquidity at risk, as the amount of liquid assets needed by a financial institution to face liquidity outflows in this scenario.
Awards and honours
Cont was awarded the Louis Bachelier Prize by the French Academy of Sciences in 2010 for his work on mathematical modelling of financial markets. Cont was elected Fellow of the Academy for the Mathematical Sciences in 2026.
Publications
Alt URL
Don’t just read it —
keep it.
Full-length biographies made to live with: read them, listen on the way to work, watch them tonight.
- E-book
- Audio
- Video
Instant download · yours to keep · every purchase keeps this site free
Important facts
People in Rama Cont's life
Named in this biography and alive at the same time
Related people
Same field, nearest in time

Contemporaries
People whose lives overlapped Rama Cont's
Frequently asked questions
Who is Rama Cont?
mathematician
When was Rama Cont born?
Rama Cont was born on 30 June 1972 in Tehran.
What is Rama Cont's occupation?
Rama Cont is a mathematician, author, university teacher, research fellow, editor-in-chief and editor.
What is Rama Cont known for?
Rama Cont is known for Model risk and Systemic risk.
What nationality is Rama Cont?
Rama Cont is French and Iranian.
Sources & further reading
Cite this page
APA: Biography.guide. (2026). Rama Cont. https://biography.guide/rama-cont/
MLA: "Rama Cont." Biography.guide, https://biography.guide/rama-cont/.
Chicago: "Rama Cont." Biography.guide. https://biography.guide/rama-cont/.
Data last updated: 2026-09-20 · Spot an error? Report a correction.
Page generated 2026-09-27 05:24 UTC