Joseph Jett
American trader
About Joseph Jett
Born 1958.
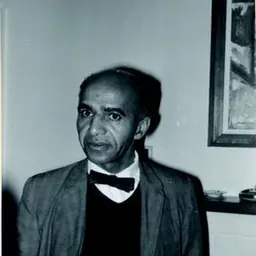
Orlando Joseph Jett (born 1958) is an American former securities trader, known for his role in the Kidder Peabody trading loss in 1994. At the time of the loss it was the largest trading fraud in history.
Jett's background Joseph Jett grew up near Cleveland, Ohio. He earned his bachelor's and master's degrees in chemical engineering at MIT and after working two years at GE Plastics went on to earn an MBA from Harvard Business School. Jett was hired by Kidder, Peabody & Co in July 1991. At the time he was 33 years old. He had worked previously as a bond trader at Morgan Stanley for two years and at First Boston for eighteen months.
Kidder Peabody At the time of Jett's employment, Kidder, Peabody & Co. was owned by General Electric Corporation, who had purchased the firm in 1986. In 1994, after numerous losses including those related to Jett, the firm was hurriedly sold to Paine Webber. After the acquisition, the Kidder Peabody name was dropped.
Jett’s trading strategy Jett's primary strategy was to exploit a flaw in Kidder's computer systems that made unprofitable trades appear profitable.
"There were virtually no genuine profitable trades. Joseph Jett, Kidder, Peabody's former bond-trading star, simply made up trades and marked them down as having made money. In the meantime, his few real trades consistently lost money."
- Floyd Norris in the New York Times
The trades used in constructing the phony profits were forward reconstitutions of US Treasury bonds. The transaction is executed when a trader buys a set of Treasury STRIPS sufficient to re-create the original bond from which they were derived.
Kidder's system incorrectly valued forward-dated transactions as if they were immediately settled, rather than taking into account the time value of money for the period before settlement of the trade. The method Jett followed was facilitated by this error. By buying US Treasury bond STRIPS (whose price increases each day due to accretion), hedged by a short Treasury bond position (whose price remains relatively stable over the settlement period), Jett was able to book immediate, illusory profits. Once settlement of the trade happened, any false profits immediately were reversed as a loss. Therefore, in order to continue to appear profitable, Jett had to engage in more and more such trades, enough to both offset the losses on the settling trades plus additional trades to keep delivering profits. For the scheme to persist, the size had to continually grow, and this is what eventually brought the scheme's downfall—Jett's trading size had become so large that General Electric, the owner of Kidder Peabody at the time, asked that he cut the size of his positions because of the bloating of GE's balance sheet. With no new trades to offset those settling and rolling off, the losses became apparent to Kidder senior management. The board of General Electric, who had owned Kidder Peabody since 1986, had to approve the outsized $9.3 million bonus in 1993.
In the first quarter of 1994, Jett was "trading" so frequently that Kidder's computer systems couldn't keep up, and his "profits" had grown to $350 million, large enough that Kidder management feared he was taking unacceptable risks.
"Jett was provided the opportunity to generate false profits by trading and accounting systems," Mr. Lynch wrote. "It was his supervisors, however, who allowed Jett that opportunity for over two years because they never understood Jett's daily trading activity or the source of his apparent profitability. Instead, their focus was on profit and loss and risk-management data that provided no insight into the mechanics of Jett's trading."
The use of Gary Lynch to conduct the internal investigation was controversial, as Lynch was also the lawyer hired by Kidder Peabody to represent the firm in its case against Jett.
Regulatory organization charges and decisions The Securities and Exchange Commission, the National Association of Securities Dealers, and the New York Stock Exchange all were involved in the various actions around the Jett case, since they all had some regulatory authority over Kidder Peabody.
The New York Stock Exchange acted first, by barring Jett from trading securities or working for any employer affiliated with the exchange. The NYSE's action effectively blackballed Jett from the securities industry.
The NASD was involved in the dispute over Jett's bonuses, which were frozen in an account held by Kidder Peabody. In 1996, a NASD arbitration panel rejected Kidder Peabody's monetary claims against Jett and ordered the funds from Jett's personal accounts to be released. Kidder had sought $8.2 million for undeserved bonuses and $74.6 million for trading losses incurred by Kidder. The $74.6 million sought by Kidder was the amount of the actual losses, rather than the total false gains of $350 million. Although the bonuses from Jett's trading had totaled $11.4 million, the accounts contained approximately $5 million due to deduction of deferred compensation (which the panel ruled, did not have to be paid to Jett) and taxes due.
The Securities and Exchange Commission investigated the losses from 1994 onward, and in 1998 released an initial ruling that Jett did not commit securities fraud, but charged him with a lesser record-keeping violation.
The SEC released an enforcement action against Jett in 2007, ordering him to pay the fines due.
The US Attorney's office investigated Jett, but no criminal charges were ever filed. about his life and experience at Kidder Peabody.
Jett has claimed to operate a hedge fund called Cambridge Matrix Funds, domiciled in the British Virgin Islands. However, the BVI Financial Services Commission, the regulator of such funds, has no listing for Cambridge Matrix in its comprehensive list of funds domiciled in the BVI.
Jett told The New York Times in 2004 that he gets between $4,000 and $8,000 per appearance on the lecture circuit.
He currently operates a firm called Jett Capital Management LLC. According to its website, the firm offers asset management, advisory, and private equity services, though it is unclear how Jett is able to perform these functions while being permanently barred from the securities industry.
In July 2008, the French news channel France 24 televised a feature following the Jérôme Kerviel trading losses, which featured an extensive interview with Jett. In it, Jett said that because of legal costs he has no money left to pay the SEC fines, and that he was living in the basement of an ex-girlfriend's house in Princeton, New Jersey. The France24 reporter said that Jett is running a financial consultancy domiciled offshore, which conducts its business from hired conference suites in New Jersey. The show televised Jett meeting with a client who was trying to raise $9 million for a business venture. At the conclusion of the report, the commentator said she believed that Jett was trying to use the France 24 program to show the SEC that he has no money to pay the fines due.
Don’t just read it —
keep it.
Full-length biographies made to live with: read them, listen on the way to work, watch them tonight.
- E-book
- Audio
- Video
Instant download · yours to keep · every purchase keeps this site free
Important facts
People in Joseph Jett's life
Named in this biography and alive at the same time
Contemporaries
People whose lives overlapped Joseph Jett's
Frequently asked questions
Who is Joseph Jett?
American trader
When was Joseph Jett born?
Joseph Jett was born in 1958.
What is Joseph Jett known for?
Joseph Jett is known for Kidder, Peabody & Co.
Sources & further reading
Cite this page
APA: Biography.guide. (2026). Joseph Jett. https://biography.guide/joseph-jett/
MLA: "Joseph Jett." Biography.guide, https://biography.guide/joseph-jett/.
Chicago: "Joseph Jett." Biography.guide. https://biography.guide/joseph-jett/.
Data last updated: 2026-09-22 · Spot an error? Report a correction.
Page generated 2026-09-27 05:25 UTC